
Mumbai, Maharashtra, 30th of October, 2026 : Financial and Operational Performance of Reliance Industries Limited (RIL) for the Quarter and Half Year ended 30th September 2026
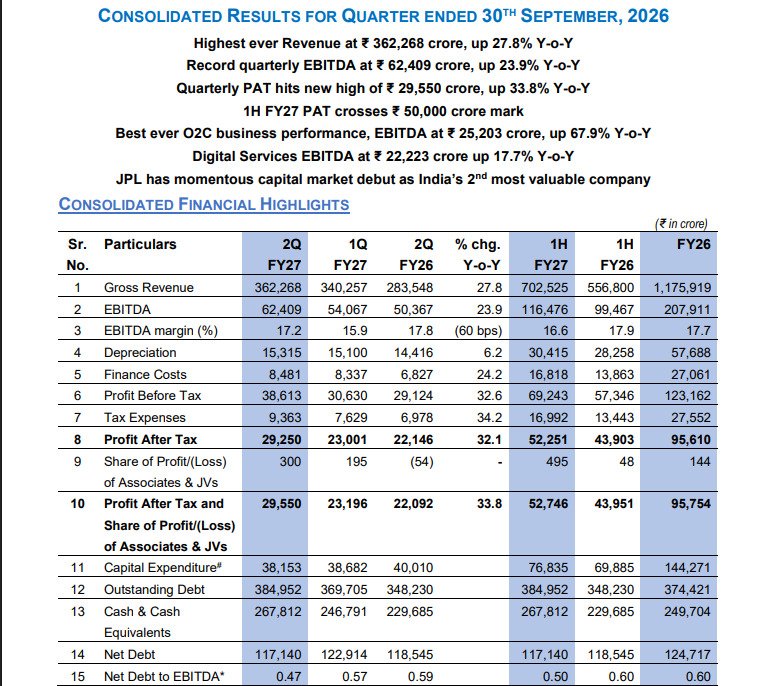

- Gross Revenue increased by 27.8% Y-o-Y to ₹ 362,268 crore ($ 37.8 billion).
- JPL revenue increased by 11.3% Y-o-Y driven by continued subscriber additions, ARPU increase and healthy growth in digital services.
- RRVL revenue grew 6.4% Y-o-Y to ₹ 91,716 crore, with performance impacted by the festive calendar shift to Q3.
- Oil to Chemicals (O2C) revenue increased by 44.2% Y-o-Y led by sharp increase in crude and product prices. Crude price for the quarter increased 40.6%, whereas transportation fuel prices were up 50-78% Y-o-Y. Prices for most of the downstream chemical products were up 25-35% Y-o-Y, driven by strong feedstock prices.
- Oil and Gas segment revenue was stable Y-o-Y. KGD6 gas production as well as price realization was lower, which was offset by higher condensate price realization. Further, improved volumes and price realization for CBM supported revenues.
- EBITDA increased by 23.9% Y-o-Y to ₹ 62,409 crore ($ 6.5 billion).
- JPL EBITDA increased by 16.6% Y-o-Y with strong revenue growth and margin expansion of 250 bps Y-o-Y.
- RRVL EBITDA decreased 8.6% Y-o-Y to ₹ 6,228 crore, with margin at 7.8%, down 120 bps Y-o-Y, reflecting planned investment phase in Digital Commerce, input-cost inflation absorbed for customers, and the festive shift to Q3.
- O2C EBITDA increased by 67.9% Y-o-Y with a steep rise in transportation fuel cracks and downstream petrochemical margins. Fuel cracks were up 3-3.7x in a very tight global refining environment. Polyester chain margins improved sharply by 33%, led by 15% higher PX delta and 52% increase in PTA delta. Earnings were constrained by higher crude oil premiums, elevated freight rates, SAED related costs and under-recoveries in domestic fuel retail.
- Oil and Gas segment EBITDA was lower by 2.0% on Y-o-Y basis on account of declining KG D6 gas revenues and higher GoI levies. This was partly offset by favourable movement in exchange rate.
- Depreciation increased by 6.2% Y-o-Y to ₹ 15,315 crore ($ 1.6 billion), largely on account of higher depreciation in Digital Services with capitalisation of 5G assets.
- Finance Costs increased by 24.2% Y-o-Y to ₹ 8,481 crore ($ 885 million), largely due to higher liability balances and capitalisation of 5G assets.
- Tax Expenses increased by 34.2% Y-o-Y at ₹ 9,363 crore ($ 977 million).
- Profit After Tax and Share of Profit/(Loss) of Associates & JVs increased by 33.8% Y-o-Y to ₹ 29,550 crore ($ 3.1 billion).
- Capital Expenditure for the quarter ended 30th September 2026, stood at ₹ 38,153 crore ($ 4.0 billion). The capex was largely driven by investments in the O2C and New Energy projects under implementation, and on building and expanding the infrastructure and distribution reach of the consumer businesses.
More Stories
IITM Mumbai 2026 Opens, Spotlighting Tourism And Destination Weddings.
Motilal Oswal Financial Services Reports 29% Yoy Growth In Operating PAT For Q2FY27, Led By 69% Growth In Asset Management.
The GCC Success Paradox: When a Centre Grows Bigger but Becomes Less Strategic.